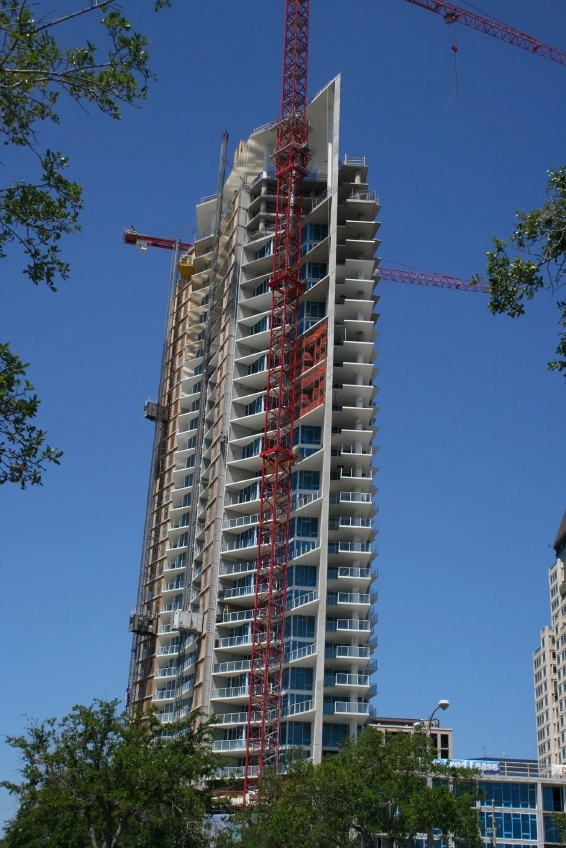
For purposes of this post, condominium hotels, or “condotels,” are essentially real estate projects or properties that combine the convenience and control of condos with the amenities of a hotel (room service, maid service, valet parking, etc.). Condotels often include a rental and/or management component that allows a third party to rent the condo owner’s unit in exchange for a portion of rental income being transferred to the unit owner.
Financing can be easier to come by for Condotels than “hotel only” or “pure hotel” properties in certain markets and the consumer demand for condotels is currently increasing in larger markets. In certain situations, the sale and marketing of condotel units can make developers and other parties involved in the project subject to United States securities laws.
Although the Supreme Court of the United States denied a petition for review of the matter, Salameh v. Tarsadia, 726 F.3d 1124 (2013), decided by the United States Court of Appeals for the Ninth Circuit provides guidance for developers creating condotel or similar projects that seek to avoid the application of United States securities law when selling condominium units. According to the Ninth Circuit’s decision in Salameh, a developer seeking to avoid having condo sales treated as sales of securities under United States law should, at a minimum, consider the following factors:
Although the Salameh decision is only binding in the Ninth Circuit, the above analysis should be considered by condotel developers anywhere within the United States. Otherwise, developers may find themselves in discussions (or worse) with the U.S. Securities and Exchange Commission and/or face private litigation or class action claims from condo unit purchasers for fraud or securities law violations.
Other resources for developers to consider on this topic:
If you are unsure if your business still needs to comply with CTA/BOI Reporting, consult with legal counsel.
View Article
As the new year has begun, so have the reporting requirements of the Corporate Transparency Act. As a follow up to our September 14, 2022 article “An Introduction to the Corporate Transparency Act,” and our December 23, 2023 article “Basic Overview of the Corporate Transparency Act (CTA),
View Article
March 1st is an annual date corporations incorporated in the State of Delaware should keep in mind because that is the due date for the Delaware annual report and franchise tax payment.
View Article
