Different transaction structures provide various tax benefits and pitfalls to buyers and sellers of businesses that may cause conflict among the parties, but a well-planned reorganization prior to a transaction can, in some cases, provide desired tax benefits to both sides of the transaction. Typically, sellers prefer the sale of equity while buyers prefer the purchase of assets. Fortunately, there are transaction structures that allow the purchase of a target’s equity to be treated as a purchase of assets for tax purposes. One such option stems from Section 368(a)(1)(F) of the Internal Revenue Code which provides a type of tax-free reorganization of a target, for potential buyers and sellers to then take advantage of when structuring the sale of a business. Commonly known as an F-type reorganization structure (or F-reorg), such method is commonly used as an M&A strategy whereby the parties structure a pre-transaction reorganization of a target to cause the equity acquisition of such target to be deemed a purchase and sale of assets for tax purposes.
Buyers typically prefer to acquire the assets of a target over equity because a buyer receives a step-up in tax basis for the acquired assets. The effect of a step-up in tax basis is “stepping up” the tax basis of assets to their fair market value upon the consummation of a proposed transaction. Post-closing, a buyer can then take tax deductions on future taxable income via the depreciation or amortization of the acquired assets. An F-reorganization structure allows a buyer to take advantage of the same step-up in tax basis for the assets of a target despite acquiring equity. Without the F-reorganization structure, assets in a straight equity purchase would simply carry over their tax basis (following the equity acquisition of the target), potentially minimizing the value of the transaction for a buyer.
An F-reorganization presumes that the surviving corporation is the same corporation as the predecessor in every respect, except for minor or technical differences. Under Section 368(a)(1)(F) of the Internal Revenue Code, an F-reorganization is a corporate reorganization by virtue of “a mere change in identify, form or place of organization, however effected.” An F-reorganization in the context of an M&A transaction typically consists of the following five (5) steps:
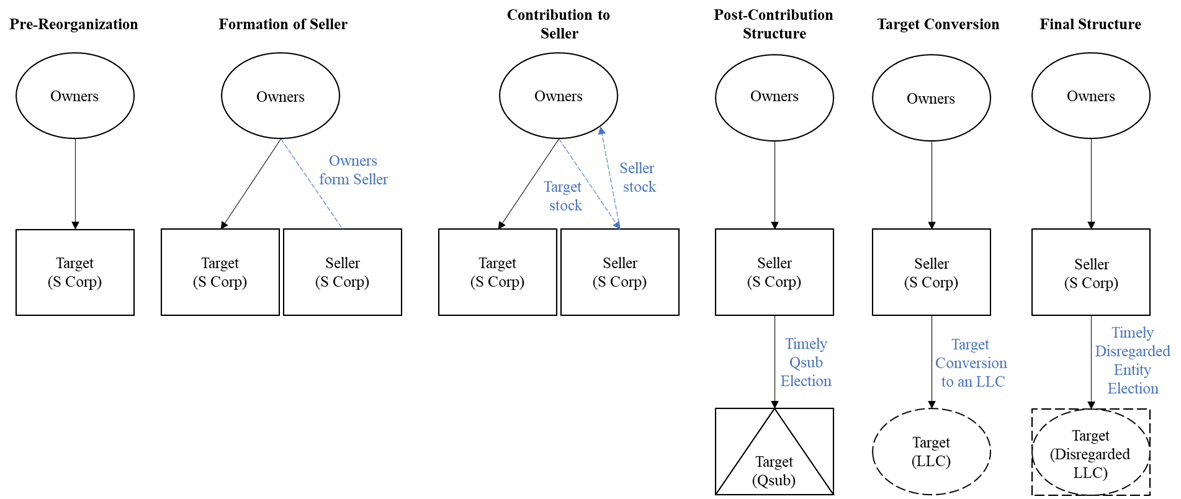
Upon completion of the F-reorganization, the owners hold all the equity interests of the seller, an S-corporation, with the target entity as its 100% owned subsidiary, a disregarded LLC. Buyers can then acquire the membership interests/units of the target entity from the seller with the purchase price flowing through to the owners. The acquisition of the target’s membership interest/units is deemed a sale and purchase of assets for tax purposes. It is important to highlight that the foregoing steps require careful planning and execution as an improper reorganization may not qualify as an F-reorganization under Section 368 of the Internal Revenue Code. More importantly, improper execution of an F-reorganization will deprive the parties of the desired tax benefits and transaction structure contemplated by the pre-transaction reorganization.
Potential benefits include the following:
Potential pitfalls or items of consideration for parties include the following:
An F-reorganization can be an efficient M&A strategy to maximize the value of the equity acquisition of a target. When planned carefully and executed correctly by professionals, a transaction structure that incorporates an F-reorganization can allow sellers to enjoy the simplicity and tax benefits of an equity sale of a business while buyers take advantage of the step-up in tax basis benefit typically achieved through an asset acquisition. Planning, beginning, and executing a potential F-reorganization and structuring an equity transaction as the sale of assets for tax purposes can be a complicated process. Navigating this process with the help of experienced professionals can be worthwhile if the benefits of an F-reorganization, notwithstanding the limitations, are right for your potential transaction.
As a buyer, understanding the industry of a target company is key to completing a thorough due diligence process. Knowing the ins and outs of an industry can help identify specific or unique due diligence matters which can raise concerns or other red flags that wouldn’t otherwise arise in another context.
View Article
Since 2020, more stringent rules have been in effect relating to transactions involving foreign nationals, which may need to be reported to the Committee on Foreign Investment in the United States (“CFIUS”) in M&A transactions.
View Article
How the Right Strategies & Timing for Mergers & Acquisitions in Downturns Can Be the Key to Greater Returns & Success
View Article
